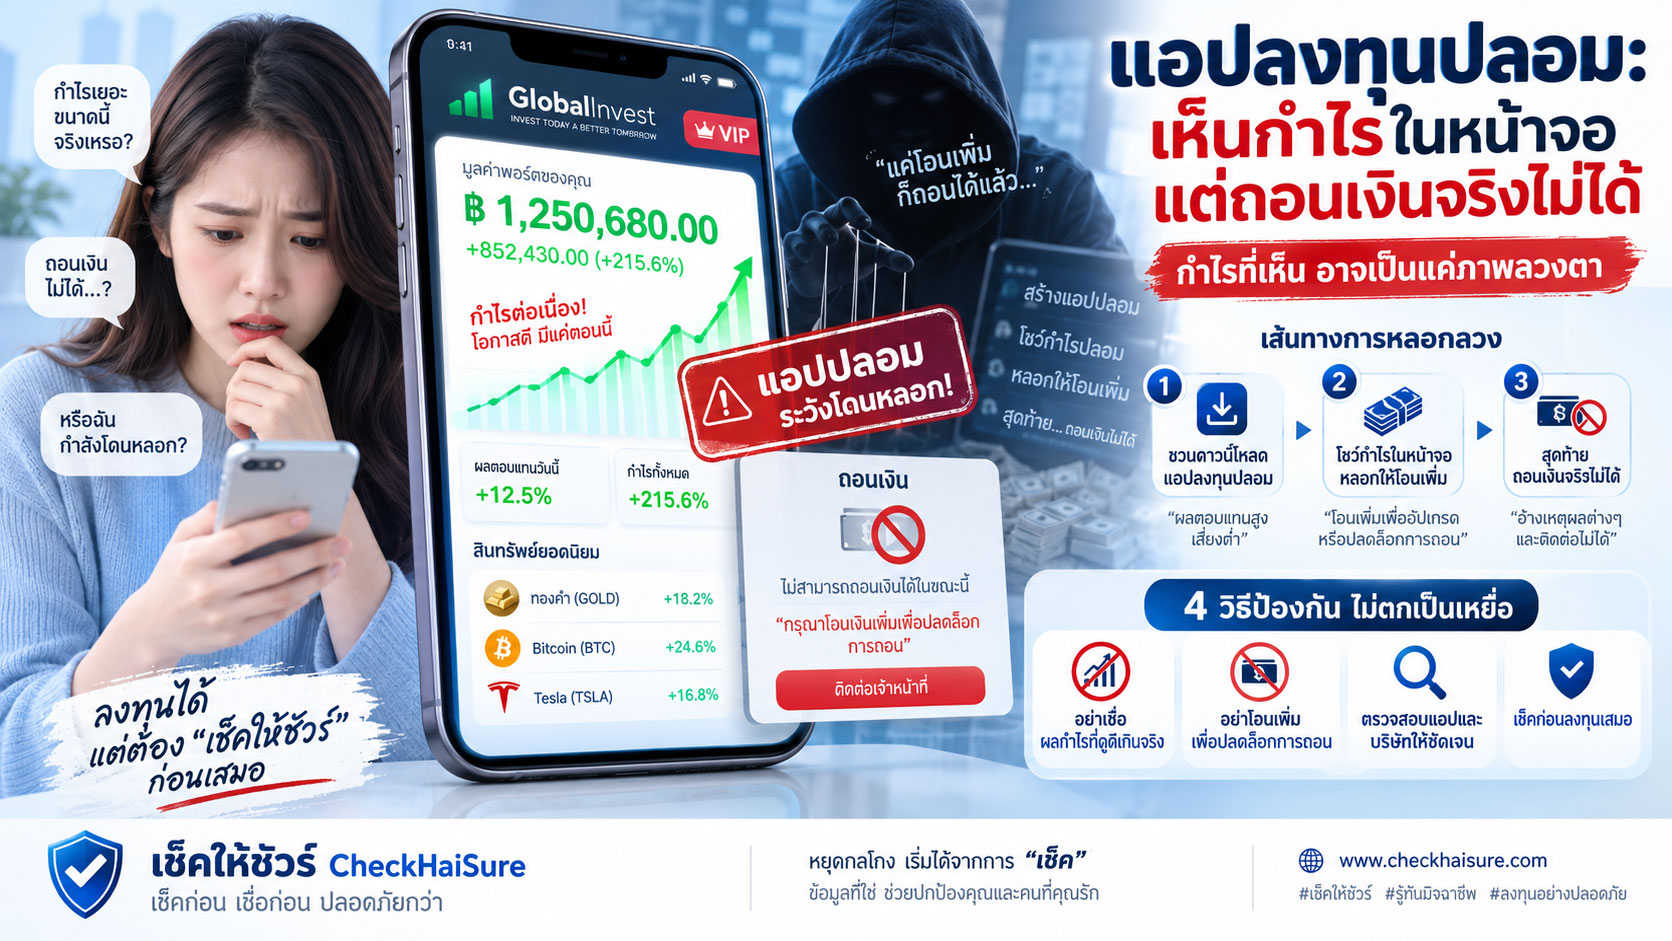
“พอร์ตคุณบวกแล้ว 18%”
“กำไรวันนี้ 12,480 บาท”
“ถ้าเติมอีก 50,000 บาท จะได้สิทธิ์เข้ากลุ่ม VIP”
“ตอนนี้เป็นจังหวะดี รีบเพิ่มทุนก่อนราคาขึ้น”
“ถอนเงินได้ครับ แต่ต้องชำระค่าภาษีก่อน”
ถ้าเราเห็นตัวเลขกำไรขึ้นทุกวัน
เห็นกราฟเขียว
เห็นยอดเงินโต
เห็นคนในกลุ่มบอกว่า “ถอนออกมาแล้ว”
มันเป็นเรื่องธรรมดามากที่จะเริ่มคิดว่า
“น่าจะเป็นของจริง”
เพราะสิ่งที่อยู่ตรงหน้าไม่ได้ดูเหมือนการถูกหลอก
มันดูเหมือนการลงทุนที่กำลังไปได้ดี
นี่คือจุดที่แอปลงทุนปลอมอันตรายกว่าการหลอกให้โอนเงินครั้งเดียว
มันไม่ได้รีบเอาเงินเราแล้วหายไปทันที
แต่มันอาจค่อย ๆ สร้าง “โลกการลงทุน” ขึ้นมารอบตัวเรา
มีกราฟ
มีบัญชี
มีผู้เชี่ยวชาญ
มีเจ้าหน้าที่
มีกลุ่มแชท
มีสมาชิกที่ดูเหมือนลงทุนจริง
มีผลตอบแทน
มี Bonus
มีระดับสมาชิก
มีประวัติซื้อขาย
และที่สำคัญที่สุด
มีตัวเลขกำไรที่ทำให้เรารู้สึกว่าเงินของเรากำลังเพิ่มขึ้นจริง
แต่คำถามที่สำคัญกว่า “กำไรเท่าไร” คือ
เงินนั้นถอนกลับเข้าบัญชีของเราได้จริงหรือไม่
กำไรบนหน้าจอ กับเงินในบัญชีธนาคาร ไม่ใช่สิ่งเดียวกัน
นี่เป็นเรื่องที่ควรจำให้ชัด
ถ้าแอปแสดงว่าเรามี 350,000 บาท
ไม่ได้แปลว่าเรามีเงิน 350,000 บาทจริงเสมอไป
ตัวเลขในแอปคือข้อมูลที่ระบบแสดงให้เราเห็น
ถ้าระบบนั้นถูกควบคุมโดยคนที่ไม่น่าไว้ใจ เขาสามารถทำให้ยอดเงินแสดงเป็นอะไรก็ได้
วันนี้ฝาก 20,000 บาท
พรุ่งนี้ขึ้นเป็น 24,000
สัปดาห์ต่อมาเป็น 31,500
อีกสองวันเป็น 38,200
เรามองแล้วรู้สึกว่า
“ทำไมไม่เคยลงทุนแบบนี้ตั้งนานแล้ว”
ตรงนี้เองที่อันตราย
เพราะตัวเลขที่สูงขึ้นทุกวัน อาจทำให้เราเริ่มคิดถึงเงินก้อนต่อไปที่จะเติมเข้าไป
ไม่ใช่เงินก้อนที่เราควรถอนออกมาทดสอบ
แอปปลอมไม่จำเป็นต้องโกงตั้งแต่วันแรก
ถ้าเริ่มต้นแล้วเงินหายทันที คนส่วนใหญ่จะรู้ตัวเร็ว
ระบบหลอกลวงที่ออกแบบมาดีจึงอาจไม่ทำแบบนั้น
ตอนแรกอาจให้เราลงเงินเพียงเล็กน้อย
5,000 บาท
10,000 บาท
หรือ 20,000 บาท
แล้วทำให้เห็นกำไรเร็ว
บางกรณีอาจยอมให้ถอนเงินจริงจำนวนเล็กน้อยด้วย
เช่น
ลง 10,000 บาท
ระบบขึ้นเป็น 12,000 บาท
ลองถอน 2,000 บาท
เงินเข้าจริง
หลังจากนั้นความรู้สึกเปลี่ยนทันที
จาก
“ไม่แน่ใจว่าเชื่อได้ไหม”
กลายเป็น
“ถอนออกมาได้จริงนี่”
แล้วจุดนี้เองอาจเป็นสิ่งที่ทำให้คนกล้าเพิ่มเงินจากหลักหมื่นเป็นหลักแสน
การถอนสำเร็จครั้งแรก จึงไม่ได้พิสูจน์เสมอไปว่าระบบปลอดภัย
บางครั้งมันอาจเป็นต้นทุนที่ใช้สร้างความเชื่อใจ
ถอนครั้งแรกได้ ไม่ได้แปลว่าจะถอนครั้งใหญ่ได้
ลองนึกภาพว่า
คุณทดลองลงทุน 10,000 บาท
ถอนกำไรออกมา 1,500 บาทได้จริง
จากนั้นเพิ่มทุนเป็น 50,000 บาท
กำไรขึ้นเป็น 68,000 บาท
เจ้าหน้าที่แนะนำให้เติมอีก
เพราะ
“ใกล้ถึงระดับ VIP”
คุณเติมอีก 100,000 บาท
ยอดในแอปกลายเป็น 230,000 บาท
ตอนนี้คุณเริ่มอยากถอน
แต่คำตอบเปลี่ยนไป
“ยอดเกินวงเงินถอน ต้องยืนยันตัวตนเพิ่ม”
“ต้องชำระภาษีก่อน”
“บัญชีติดตรวจสอบ”
“ต้องเติมหลักประกัน”
“ต้องชำระค่าธรรมเนียมปลดล็อก”
จากเงินที่เราอยากถอน
กลับกลายเป็นเราต้องหาเงินมาโอนเพิ่ม
นี่เป็นสัญญาณอันตรายที่สำคัญมาก
คำว่า “จ่ายก่อน แล้วจะถอนทั้งหมดได้” ควรทำให้เราหยุด
เมื่อถอนเงินไม่ได้ มิจฉาชีพมักสร้างเหตุผลใหม่
เช่น
ค่าภาษี
ค่าธรรมเนียมถอน
ค่าปลดล็อก
ค่าประกันบัญชี
ค่าตรวจสอบ AML
ค่าคอมมิชชัน
ค่ารับรองตัวตน
ค่ารักษาสถานะสมาชิก
หรือค่าปรับเพราะทำรายการผิด
ชื่ออาจดูเป็นทางการมาก
แต่รูปแบบเหมือนกันคือ
เราต้องโอนเงินจริงเพิ่ม เพื่อหวังว่าจะได้ถอนเงินที่เห็นอยู่บนหน้าจอ
ตรงนี้ควรหยุด
เพราะถ้าเงินในบัญชีลงทุนเป็นของเราจริง ควรถามได้ว่า
ทำไมค่าธรรมเนียมหรือภาษีบางอย่างจึงไม่สามารถหักจากยอดที่มีอยู่ได้
ทำไมต้องให้เราโอนเงินใหม่เข้าไปอีก
และเงินที่โอนไปนั้นเข้าบัญชีของใคร
“เงินค้างในระบบ” เป็นประโยคที่ทำให้คนยอมจ่ายต่อได้ง่ายมาก
สมมติยอดในแอปขึ้นว่า 480,000 บาท
เราถอนออกไม่ได้
เจ้าหน้าที่บอกว่า
“ต้องจ่าย 28,000 บาทเพื่อปลดล็อก”
ตอนนี้สมองเราไม่ได้เห็นแค่เงิน 28,000
แต่มองเห็นเงิน 480,000 ที่คิดว่าเป็นของเราอยู่แล้ว
เราจึงอาจคิดว่า
“เสียอีก 28,000 เพื่อเอา 480,000 ออกมา ก็คุ้ม”
นี่คือแรงกดดันที่รุนแรงมาก
ยิ่งยอดในแอปสูง
เรายิ่งรู้สึกว่าควรจ่ายเพิ่มเพื่อรักษาเงินก้อนใหญ่
แต่ต้องจำว่า
ยอดที่ถอนออกมาไม่ได้ ยังไม่ควรถูกมองว่าเป็นเงินที่เราเป็นเจ้าของได้จริง
อย่าใช้เงินที่ “เห็น” เป็นเหตุผลให้เสียเงินจริงเพิ่ม
นี่เป็นกฎที่สำคัญมาก
ถ้าหน้าจอขึ้นว่า
กำไร 1 ล้านบาท
แต่ต้องจ่าย 70,000 บาทก่อนถึงจะถอน
อย่าให้ตัวเลข 1 ล้านบาทเป็นเหตุผลให้โอน 70,000
เพราะสิ่งที่มีมูลค่าจริง ณ เวลานั้นคือ
70,000 บาทที่ยังอยู่ในบัญชีธนาคารของเรา
ส่วน 1 ล้านบาทนั้นอาจเป็นเพียงตัวเลขในระบบที่อีกฝ่ายควบคุม
อย่าเอาเงินจริง ไปแลกกับความหวังว่าจะได้ตัวเลขในหน้าจอออกมาเป็นเงินจริง
กลุ่มแชทที่ทุกคนกำไร อาจทำให้เราเชื่อมากกว่าตัวแอปเอง
บางคนไม่ได้เชื่อแค่แอป
แต่เชื่อเพราะกลุ่ม
ในกลุ่มอาจมีคนพูดว่า
“วันนี้กำไรอีกแล้วครับ”
“ขอบคุณอาจารย์ค่ะ ถอนมาแล้ว 80,000”
“ใครยังไม่เพิ่มทุนเสียดายมาก”
“รอบคืนนี้น่าจะขึ้นแรง”
มีภาพสลิป
ภาพพอร์ต
ภาพรถ
ภาพอาหารหรู
หรือคนพูดถึงกำไรต่อเนื่อง
เมื่อเราเห็นคนจำนวนมากพูดเรื่องเดียวกัน เราจะรู้สึกว่า
“ไม่น่าจะปลอมได้หมด”
แต่สิ่งที่เราไม่รู้คือ
สมาชิกเหล่านั้นเป็นใครบ้าง
เป็นนักลงทุนจริงหรือไม่
เป็นบัญชีที่ทีมเดียวกันควบคุมหรือไม่
ภาพสลิปจริงหรือไม่
และข้อความที่เราเห็นเป็นบทสนทนาธรรมชาติ หรือเป็นสิ่งที่ถูกวางไว้เพื่อสร้างบรรยากาศ
จำนวนคนในกลุ่ม ไม่ใช่หลักฐานว่าการลงทุนจริง
“อาจารย์” หรือ “ผู้เชี่ยวชาญ” ที่ทายถูกหลายครั้ง อาจยังไม่พิสูจน์อะไร
อีกสิ่งหนึ่งที่สร้างความเชื่อใจคือคนที่ดูเหมือนรู้ตลาดมาก
เขาอาจบอกว่า
“เข้าตรงนี้”
“ขายตรงนี้”
“วันนี้ทองจะขึ้น”
“คืนนี้คริปโตจะวิ่ง”
แล้วระบบในแอปก็แสดงว่าเราได้กำไร
เราจึงเริ่มคิดว่า
“คนนี้แม่นจริง”
แต่ถ้าแพลตฟอร์มที่เราเห็นราคาและกำไรเป็นแพลตฟอร์มเดียวกับที่อีกฝ่ายควบคุม เราอาจไม่ได้กำลังดูผลตลาดจริงทั้งหมด
สิ่งที่เห็นอาจถูกจัดวางให้สอดคล้องกับคำแนะนำของเขา
ดังนั้นอย่าตัดสินความน่าเชื่อถือของผู้แนะนำจากกำไรที่เกิดขึ้นเฉพาะในระบบที่เขาเป็นคนพาเราเข้าไป
จากคำว่า “ลองนิดเดียว” ไปถึงเงินเก็บทั้งชีวิตได้อย่างไร
หลายคนไม่ได้เริ่มจากความโลภ
เริ่มจาก
“ลองดู 5,000 บาท”
แล้วได้กำไร
จากนั้นคิดว่า
“ถ้าลง 50,000 กำไรคงมากขึ้น”
แล้วเจ้าหน้าที่พูดว่า
“ถ้าเพิ่มเป็น 100,000 จะได้ผลตอบแทนดีกว่า”
ต่อมามีโปรโมชัน
“เติมวันนี้รับโบนัส 20%”
จากนั้นเป็น
“ยอดอีกนิดเดียวจะได้ VIP”
เงินจึงค่อย ๆ เพิ่ม
5,000
20,000
50,000
100,000
300,000
บางคนเริ่มนำเงินเก็บมาใช้
บางคนขายทอง
บางคนกดบัตร
บางคนยืมเงิน
เพราะในใจคิดว่า
“ไม่ได้เสีย เงินอยู่ในพอร์ต”
นี่คือจุดอันตราย
เพราะเงินอาจออกจากโลกจริงไปแล้ว
แต่ความมั่นใจมาจากตัวเลขในโลกของแอป
Bonus ที่ดูเหมือนเงินฟรี อาจทำให้ถอนยากขึ้น
บางแพลตฟอร์มอาจบอกว่า
“ฝาก 100,000 รับโบนัส 30,000”
เห็นแล้วเหมือนได้เงินฟรี
แต่ต้องอ่านเงื่อนไขให้ชัด
โบนัสอาจถูกใช้เป็นเหตุผลให้
ต้องซื้อขายครบยอดก่อน
ต้องรักษายอดเงินขั้นต่ำ
ต้องเพิ่มเงินอีก
หรือยังถอนยอดทั้งหมดไม่ได้
ในระบบหลอกลวง Bonus ยังอาจเป็นเพียงตัวเลขอีกตัวที่ใช้ทำให้ยอดรวมดูสูงขึ้น
อย่าตัดสินว่าดีลคุ้มจากยอด Bonus
ให้ดูว่าเงินต้นของเราถอนได้อย่างอิสระจริงหรือไม่
“ใกล้ได้ VIP แล้ว” เป็นอีกวิธีที่ทำให้เราไม่หยุด
ระบบอาจมีระดับ
Silver
Gold
Platinum
VIP
Diamond
และบอกว่า
“อีก 30,000 บาทจะขึ้น Gold”
หรือ
“VIP ถอนเงินได้เร็วกว่า”
จากการลงทุน
เริ่มกลายเป็นเกมสะสมระดับ
เรารู้สึกเสียดาย ถ้าขาดอีกนิดเดียว
นี่คล้ายกับความรู้สึกว่า
“มาไกลแล้ว ถอยตอนนี้เสียดาย”
แต่ต้องจำว่า
ระดับสมาชิกในหน้าจอ ไม่มีความหมายเท่ากับความสามารถในการถอนเงินกลับออกมา
คำว่า “โอกาสมีแค่คืนนี้” ทำให้เราไม่มีเวลาตรวจสอบ
การลงทุนปลอมมักชอบความเร่งด่วน
“คืนนี้มีข่าวใหญ่”
“ต้องเข้าก่อนตลาดเปิด”
“รอบนี้มีเฉพาะสมาชิก”
“อีก 20 นาทีปิดรับ”
“ถ้าไม่เพิ่มทุนตอนนี้จะพลาด”
ความเร่งด่วนทำให้เราไม่มีเวลา
ค้นชื่อบริษัท
ตรวจสอบใบอนุญาต
ถามคนอื่น
ทดลองถอน
หรือกลับมาคิดใหม่
โอกาสลงทุนจริงอาจมีความผันผวนและมีช่วงเวลา
แต่การถูกบังคับให้ตัดสินใจโดยไม่มีเวลาตรวจสอบ ควรเป็นเหตุผลให้ช้าลง
ไม่ใช่เร็วขึ้น
ยิ่งเขาพยายามห้ามถอน ยิ่งต้องคิดเรื่องถอนก่อนเพิ่มเงิน
ถ้าเราบอกว่า
“อยากถอนกำไรก่อน”
แล้วอีกฝ่ายตอบว่า
“อย่าเพิ่งถอน เสียโอกาส”
“ตอนนี้กำไรดี ให้ทบไปก่อน”
“ถอนตอนนี้เสีย Bonus”
“รออีกสองวันกำไรจะมากกว่า”
ลองถามตัวเองว่า
ทำไมเขาถึงกังวลมากกับการที่เราเอาเงินของเราเองออก
การทดลองถอนเงินเป็นหนึ่งในสิ่งที่ช่วยให้เราเห็นความแตกต่างระหว่าง
“ตัวเลขในระบบ”
กับ
“เงินที่เราควบคุมจริง”
ถ้าแค่พูดว่าจะถอนก็เริ่มถูกกดดัน ให้ระวังมากขึ้น
อย่ามองแค่กราฟ ให้ดูว่าเงินถูกโอนไปที่ไหน
เวลา “ลงทุน” จริง เงินของเราไปที่ใด
คำถามนี้สำคัญกว่ากราฟสวย
ถ้าเราโอนเงินไป
บัญชีบุคคล
บัญชีที่เปลี่ยนไปเรื่อย ๆ
ชื่อบัญชีไม่ตรงบริษัท
มีคนบอกว่าเป็นบัญชีตัวแทน
บัญชีฝ่ายการเงิน
บัญชีรับฝาก
หรือให้โอนหลายบัญชีสลับกัน
ให้สงสัยทันที
คนปลายสายอาจบอกว่า
“เป็น Payment Gateway”
“บัญชีของบริษัทในเครือ”
“บัญชีรับเงินของ Dealer”
“ระบบกำลังเปลี่ยนบัญชี”
คำอธิบายอาจฟังเป็นธุรกิจ
แต่ก่อนโอนเงินลงทุนจริง ควรรู้ให้ชัดว่าเงินกำลังไปที่ใครและภายใต้ความสัมพันธ์ทางกฎหมายอะไร
แอปอยู่ใน Store ก็ยังต้องตรวจผู้ให้บริการ
เหมือนกับแอปประเภทอื่น
การพบแอปใน Store ช่วยลดความเสี่ยงบางอย่างเมื่อเทียบกับการโหลดจากลิงก์แปลก
แต่ไม่ควรใช้เป็นหลักฐานเพียงอย่างเดียวว่าการลงทุนถูกต้อง
ต้องดูต่อว่า
บริษัทผู้ให้บริการคือใคร
เว็บไซต์อะไร
มีข้อมูลนิติบุคคลหรือไม่
ใครเป็นผู้ดำเนินการ
บริการที่เสนอคืออะไร
การรับฝากเงินเกิดขึ้นอย่างไร
และมีช่องทางตรวจสอบจากแหล่งอิสระหรือไม่
แอปอาจดูดี
แต่สิ่งที่เราลงทุนด้วยคือเงินจริง
เราควรตรวจผู้รับเงินจริงให้ละเอียดกว่าการดูไอคอนแอป
ถ้าให้โหลด APK หรือแอปจากลิงก์ส่วนตัว ยิ่งต้องระวัง
บางกลโกงจะให้ติดตั้งแอปที่ไม่ได้อยู่ใน Store
บอกว่า
“เป็นแอปสำหรับสมาชิก”
“เวอร์ชันนี้ผลตอบแทนสูงกว่า”
“ดาวน์โหลดจากลิงก์ของอาจารย์”
“เป็นระบบ Private”
“Store ยังไม่รองรับ”
จุดนี้มีความเสี่ยงเพิ่มขึ้นสองชั้น
ชั้นแรกคือการลงทุนอาจไม่จริง
ชั้นที่สองคือเราไม่รู้ว่าแอปที่ติดตั้งกำลังทำอะไรในมือถือ
ถ้าการลงทุนที่ตรวจสอบไม่ได้ ยังต้องให้เราลดความปลอดภัยของมือถือเพื่อเข้าร่วมด้วย
ควรหยุดอย่างจริงจัง
ตัวเลขตลาดจริง ไม่ได้ทำให้แพลตฟอร์มจริง
นี่เป็นจุดที่หลายคนถูกโน้มน้าวได้ง่าย
แอปอาจแสดง
ราคาทองจริง
ราคาคริปโตจริง
กราฟตลาดจริง
ข่าวเศรษฐกิจจริง
เมื่อข้อมูลบางส่วนตรง เราจึงคิดว่าระบบทั้งหมดจริง
แต่การดึงข้อมูลราคาจริงมาแสดง ไม่ได้พิสูจน์ว่าเงินที่เราฝากถูกนำไปลงทุนจริง
เว็บไซต์หรือแอปสามารถแสดงราคาตลาดจริงได้
พร้อมกับสร้างยอดบัญชีของเราเองขึ้นมาอีกส่วนหนึ่ง
ดังนั้น
“ราคาในแอปตรงกับ Google”
ไม่ได้แปลว่า
“เงินของเราอยู่ในตลาดจริง”
สัญญาณเตือนของแอปลงทุนปลอม
ถ้าเจอหลายข้อพร้อมกัน ควรหยุดเพิ่มเงินและตรวจสอบก่อน
มีคนแปลกหน้าชวนลงทุนผ่านแชท
รู้จักผ่าน Dating App หรือ Social Media แล้วพาไปลงทุน
รับประกันกำไร
บอกว่าขาดทุนยากหรือแทบไม่มีความเสี่ยง
แสดงกำไรสูงต่อเนื่องผิดปกติ
ให้โอนไปบัญชีบุคคล
เปลี่ยนบัญชีรับเงินบ่อย
ให้โหลดแอปจากลิงก์หรือ APK
มี “อาจารย์” บอกจังหวะซื้อขายแทบทุกครั้ง
คนในกลุ่มทุกคนเหมือนกำไร
เร่งให้เพิ่มเงิน
เสนอ Bonus ถ้าเติมเพิ่ม
ใช้ระดับ VIP กดดันให้ลงทุนมากขึ้น
พยายามห้ามถอน
ถอนเงินจำนวนเล็กได้ แต่ยอดใหญ่ไม่ได้
ขอค่าธรรมเนียมก่อนถอน
ขอภาษีก่อนถอน
ขอเงินปลดล็อกบัญชี
บอกว่าต้องเติมเงินเพิ่มเพื่อแก้รายการผิด
หรือทุกครั้งที่จ่ายแล้วกลับมีค่าใช้จ่ายใหม่เพิ่มมาอีก
ถ้าเริ่มเห็นลำดับนี้ อย่ารอจนเสียทุกอย่างก่อนจึงหยุด
ก่อนลงทุนผ่านแอป ลองถามตัวเอง 8 ข้อ
- บริษัทที่รับเงินของฉันคือใคร?
- ฉันตรวจสอบบริษัทนี้จากแหล่งที่ไม่ใช่คนที่ชวนลงทุนแล้วหรือยัง?
- เงินที่โอนไปเข้าชื่อใคร?
- ถ้าจะถอนเงินต้นตอนนี้ ทำได้หรือไม่?
- ผลตอบแทนที่เห็นมีที่มาชัดเจนหรือไม่?
- ถ้าฉันไม่เพิ่มเงินวันนี้ จะเกิดอะไรขึ้นจริง ๆ?
- ทำไมฉันจึงต้องจ่ายเงินใหม่เพื่อถอนเงินเก่า?
- ถ้าปิดแชทกับคนชวนลงทุนทั้งหมด ฉันยังสามารถติดต่อบริษัทผ่านช่องทางทางการได้หรือไม่?
ข้อแปดสำคัญมาก
ถ้าทุกอย่างหายไปพร้อมกับคนใน LINE
ความสัมพันธ์นั้นอาจไม่เหมือนการลงทุนกับสถาบันที่ตรวจสอบได้
ทดลองถอน สำคัญกว่าดูเปอร์เซ็นต์กำไร
คนมักถามว่า
“กำไรเท่าไร”
แต่คำถามที่ควรถามบ่อยกว่าคือ
“ถอนออกได้ไหม”
และไม่ใช่แค่ถอน 500 หรือ 1,000 บาท
ต้องดูด้วยว่า
ถอนเงินต้นได้ไหม
ถอนจำนวนที่มีนัยสำคัญได้ไหม
มีข้อจำกัดอะไร
มีค่าธรรมเนียมอะไร
และเงื่อนไขเหล่านั้นมีบอกไว้ตั้งแต่ก่อนฝากเงินหรือเพิ่งเกิดตอนจะถอน
กำไร 40% ที่ถอนออกไม่ได้ อาจมีค่าน้อยกว่าเงินต้น 100% ที่ยังอยู่ในบัญชีเราเอง
ถ้าถอนไม่ได้ อย่าใช้วิธีเติมเงินเพื่อแก้ปัญหาทันที
ถ้าระบบบอกว่า
ถอนล้มเหลว
บัญชีถูกล็อก
ต้องยืนยันใหม่
อย่าให้การแก้ปัญหาแรกเป็น
“เติมเงิน”
หยุดก่อน
เก็บภาพหน้าจอ
เก็บข้อความ
เก็บชื่อแพลตฟอร์ม
เก็บบัญชีที่เคยโอน
แล้วตรวจสอบจากแหล่งอื่น
เพราะถ้าทุกปัญหามีคำตอบเหมือนกันว่า
“โอนเพิ่ม”
นั่นไม่ใช่รูปแบบที่ควรทำต่อโดยไม่ตรวจสอบ
ถ้าโอนไปมากแล้ว ความรู้สึก “เสียดาย” จะทำให้หยุดยากขึ้น
สมมติเราใส่ไปแล้ว 300,000 บาท
พอเริ่มสงสัย เราจะไม่อยากยอมรับว่าอาจเกิดปัญหา
เพราะถ้ายอมรับ
หมายความว่าเงิน 300,000 อาจเสี่ยง
เราจึงมีแนวโน้มอยากเชื่อประโยคว่า
“จ่ายอีก 30,000 แล้วถอนหมดได้”
นี่ไม่ใช่เพราะเราโง่
แต่มนุษย์ทุกคนไม่อยากสูญเสียสิ่งที่ลงทุนไปแล้ว
จุดนี้ควรใช้กฎง่าย ๆ
เงินที่จ่ายไปแล้ว ไม่ควรเป็นเหตุผลให้จ่ายเพิ่มโดยไม่มีหลักฐานใหม่ที่ตรวจสอบได้
ถ้ารู้ตัวว่าอาจเป็นแอปลงทุนปลอม ควรทำอย่างไร
หยุดโอนเงินเพิ่มก่อน
อย่ารีบจ่าย “ค่าถอน” ก้อนต่อไป
เก็บหลักฐานให้มากที่สุด
เช่น
ชื่อแอป
เว็บไซต์
ลิงก์
ชื่อผู้ชวน
บัญชี LINE
เบอร์โทร
กลุ่มแชท
ข้อความ
ภาพพอร์ต
ประวัติฝากถอน
เลขบัญชีที่โอน
ชื่อบัญชีปลายทาง
สลิป
วันเวลา
ยอดเงิน
และข้อความที่บอกให้จ่ายเงินเพิ่ม
ถ้ามี APK หรือไฟล์แอปที่ดาวน์โหลดมา ให้เก็บข้อมูลต้นทางไว้ด้วย
จากนั้นติดต่อธนาคารผ่านช่องทางทางการ หากมีการโอนเงินเกี่ยวข้อง
และแจ้งเหตุผ่านช่องทางที่เกี่ยวข้อง
อย่าลบแชทเพราะอาย
ถ้าแอปขอ Remote Access หรือสิทธิ์แปลก ๆ ให้มองเป็นอีกความเสี่ยงหนึ่งทันที
การหลอกลงทุนกับการขโมยข้อมูลมือถืออาจเกิดพร้อมกันได้
ถ้าแพลตฟอร์มลงทุนบอกให้
เปิด Accessibility
แชร์หน้าจอ
ให้เจ้าหน้าที่รีโมต
เปิด Mobile Banking ให้ดู
หรือให้ OTP
ให้หยุดทันที
การลงทุนไม่ควรต้องให้คนแปลกหน้าเข้ามาควบคุมโทรศัพท์ของเรา
จากเรื่องเสียเงินลงทุน อาจกลายเป็นความเสี่ยงต่อบัญชีอื่น ๆ เพิ่มอีก
ถ้าเริ่มรู้ตัวว่าถูกหลอก อย่าเก็บไว้คนเดียว
บางคนไม่กล้าบอกครอบครัว
เพราะเงินที่เสียเป็นเงินเก็บ
หรือเคยถูกเตือนแล้ว
หรือยืมคนอื่นมาลงทุน
หรือรู้สึกว่า
“ไม่น่าพลาดเลย”
แต่การเก็บไว้คนเดียวทำให้มิจฉาชีพยังมีพื้นที่กดดันต่อ
เขาอาจพูดว่า
“อย่าบอกใคร เดี๋ยวถอนยาก”
“คนอื่นไม่เข้าใจระบบ”
“มีแค่สมาชิกเท่านั้นที่รู้”
ถ้าเริ่มสงสัย ให้ดึงคนที่ไว้ใจเข้ามาช่วยดู
คนที่ไม่ได้อยู่ในวงการสนทนามาตั้งแต่ต้น อาจมองเห็นสิ่งผิดปกติได้ชัดกว่าเรา
คนในครอบครัวควรช่วยก่อน อย่ารีบพูดว่า “บอกแล้วว่าอย่าลงทุน”
ถ้ามีคนมาบอกว่า
“ถอนเงินไม่ได้”
สิ่งแรกที่ควรช่วยคือหาว่า
โอนไปเท่าไร
โอนไปบัญชีไหน
ยังมีคำสั่งให้โอนเพิ่มหรือไม่
มีข้อมูลอะไรถูกให้ไปแล้ว
มีการติดตั้งแอปอะไร
มี Remote Access หรือไม่
และมีหลักฐานอะไรเก็บไว้บ้าง
คำว่า
“บอกแล้ว”
ไม่ได้ช่วยให้เงินกลับมา
แต่การหยุดโอนครั้งต่อไปได้ อาจช่วยรักษาเงินที่ยังเหลืออยู่
อย่าโทษตัวเองเพราะเคยเห็นกำไรแล้วเชื่อ
ถ้าคุณเห็นกำไรขึ้นจริงในแอป
เคยถอนเงินออกมาได้บางส่วน
เห็นคนอื่นโชว์สลิป
และพูดคุยกับคนเดิมมาหลายสัปดาห์
การเชื่อว่าระบบเป็นของจริง ไม่ใช่เรื่องน่าแปลก
กลโกงที่ซับซ้อนไม่ได้พยายามทำให้ดูน่าสงสัย
มันพยายามทำให้ดูน่าเชื่อ
สิ่งสำคัญคือเมื่อเริ่มมีจุดที่ไม่สมเหตุสมผล
เช่น
ถอนเงินไม่ได้
ต้องโอนเพิ่ม
เงื่อนไขเปลี่ยน
มีค่าธรรมเนียมใหม่
หรือเริ่มถูกกดดัน
ให้ยอมกลับมาถามใหม่ว่า
เงินจริงของเราอยู่ตรงไหน
ประโยคที่ควรจำ: กำไรที่ถอนออกมาไม่ได้ ยังไม่ใช่กำไรที่เราควรนับ
ถ้าต้องจำเพียงประโยคเดียวจากบทความนี้ ขอให้จำว่า
กำไรที่ถอนออกมาไม่ได้ ยังไม่ใช่กำไรที่เราควรนับ
กราฟเขียวสวยได้
ยอดเงินเพิ่มได้
Bonus เพิ่มได้
ระดับ VIP เพิ่มได้
แต่ทั้งหมดนั้นยังอยู่ในระบบที่คนอื่นควบคุม
สิ่งที่สำคัญคือ
เราถอนเงินต้นกลับมาได้หรือไม่
เราเป็นคนควบคุมเงินหรือไม่
และเวลาถอนต้องเอาเงินจริงก้อนใหม่เข้าไปแลกหรือไม่
ถ้าต้องจ่ายเพิ่มทุกครั้งที่ขอเอาเงินของตัวเองออก
ให้หยุดก่อน
สรุป: แอปลงทุนปลอมไม่ได้หลอกด้วยคำว่า “ขาดทุน” แต่มักหลอกด้วยคำว่า “กำไร”
คนส่วนใหญ่อาจคิดว่ามิจฉาชีพจะทำให้เงินเราหาย
แต่แอปลงทุนปลอมอาจทำตรงข้าม
มันทำให้เงินบนหน้าจอเพิ่มขึ้น
เพราะเมื่อเราเห็นว่า
10,000 กลายเป็น 15,000
50,000 กลายเป็น 80,000
200,000 กลายเป็น 350,000
เราจะอยากเติมมากขึ้น
และยิ่งยอดสูง เราก็ยิ่งยอมจ่ายค่าต่าง ๆ เพื่อพยายามถอนมันออกมา
ตรงนี้คือสิ่งที่ควรระวังที่สุด
ก่อนเพิ่มทุน
ทดลองถอน
ก่อนเชื่อกำไร
ตรวจสอบผู้รับเงิน
ก่อนโอนเข้าบัญชีใหม่
ถามว่าทำไมเปลี่ยนบัญชี
ก่อนจ่ายค่าถอน
ถามว่าทำไมไม่หักจากยอดเดิม
และก่อนเชื่อกราฟ
ถามว่าเงินจริงของเราอยู่ที่ไหน
เพราะในโลกการลงทุน
ตัวเลขที่สวยที่สุดไม่ใช่ตัวเลขกำไรบนหน้าจอ
แต่คือเงินที่เรายังสามารถควบคุม และนำกลับเข้าบัญชีของเราเองได้จริง
Fake Investment Apps: The Profits Look Real on Screen, but You Cannot Withdraw the Money
“Your portfolio is up 18%.”
“Today’s profit: 12,480 baht.”
“If you add another 50,000 baht, you will qualify for VIP status.”
“This is a good entry point. Add more capital before the price rises.”
“You can withdraw the money, but you need to pay the tax first.”
If you see profits increasing every day,
green charts,
a growing balance,
and people in the group saying, “I already withdrew successfully,”
it is completely natural to start thinking:
“This must be real.”
Because what you are looking at does not feel like a scam.
It looks like an investment that is doing very well.
That is what makes fake investment apps more dangerous than a simple one-time money transfer scam.
They may not take your money and disappear immediately.
Instead, they may slowly build an entire “investment world” around you.
There is a chart.
An account balance.
An expert.
A customer service officer.
A group chat.
Other members who appear to be real investors.
Returns.
Bonuses.
Membership levels.
Trading history.
And most importantly:
A profit number that makes you feel your money is genuinely growing.
But the more important question is not:
“How much profit am I making?”
It is:
Can that money actually be withdrawn into an account you control?
Profit on a Screen Is Not the Same as Money in Your Bank Account
This is one of the most important things to remember.
If an app says you have 350,000 baht,
that does not automatically mean you truly own 350,000 baht.
The number inside an app is simply information displayed by the system.
If that system is controlled by people you cannot trust, they may be able to make the balance show almost anything.
You deposit 20,000 baht today.
Tomorrow it becomes 24,000.
A week later it shows 31,500.
Two days after that it reaches 38,200.
You start thinking:
“Why didn’t I start investing like this earlier?”
That is where the danger begins.
Because when the number keeps rising, you may start thinking about how much more money you should add.
Instead of asking whether you should first try to withdraw the money already there.
A Fake Investment App Does Not Have to Scam You on the First Day
If your money disappeared immediately, most people would realize something was wrong very quickly.
A well-designed scam may do the opposite.
At first, it may encourage you to invest only a small amount.
5,000 baht.
10,000 baht.
20,000 baht.
Then the app shows a quick profit.
In some cases, the system may even allow a small real withdrawal.
For example:
You deposit 10,000 baht.
The app shows 12,000.
You withdraw 2,000 baht.
And the money really arrives.
Your thinking changes immediately.
From:
“I’m not sure I trust this.”
To:
“It really pays out.”
That small successful withdrawal can become the reason someone later feels comfortable increasing their investment from tens of thousands to hundreds of thousands.
So a successful first withdrawal does not automatically prove the platform is safe.
Sometimes it may simply be the cost of gaining your trust.
A Small Withdrawal Can Work Even When a Large Withdrawal Will Not
Imagine this:
You test the platform with 10,000 baht.
You withdraw 1,500 baht of profit successfully.
Then you increase your investment to 50,000 baht.
The balance grows to 68,000.
The “advisor” encourages you to add more.
“You are close to VIP status.”
So you add another 100,000 baht.
Now the app shows 230,000 baht.
You decide to withdraw.
Suddenly, the rules change.
“Your withdrawal exceeds the limit. Additional verification is required.”
“You must pay tax first.”
“Your account is under review.”
“You need to add a security deposit.”
“You need to pay an account unlocking fee.”
The moment you try to take money out,
the system begins asking you to put more money in.
That is a major warning sign.
“Pay First, Then You Can Withdraw Everything” Should Make You Stop
When a withdrawal fails, scammers may create a new reason.
They may call it:
Tax
Withdrawal fee
Unlocking fee
Account insurance
AML verification fee
Commission
Identity certification fee
Membership maintenance fee
Or a penalty for an incorrect transaction
The name may sound official.
But the pattern is the same:
You are asked to send more real money in the hope of withdrawing money that only appears on the screen.
That is the point where you should stop.
If the investment balance really belongs to you, it is reasonable to ask:
Why can certain fees or taxes not be deducted from the existing balance?
Why do I need to send new money again?
And whose account am I actually sending that money to?
“Your Money Is Stuck in the System” Is a Powerful Way to Make People Keep Paying
Imagine the app shows a balance of 480,000 baht.
You try to withdraw.
It fails.
The officer says:
“You need to pay 28,000 baht to unlock the account.”
At that moment, your brain is not only thinking about losing 28,000 baht.
You are thinking about the 480,000 baht you already believe belongs to you.
So you may think:
“Paying another 28,000 to recover 480,000 is worth it.”
That pressure can be extremely strong.
The larger the balance shown on the app,
the more willing a person may become to send additional money to “protect” it.
But remember:
Money that cannot be withdrawn should not yet be treated as money you truly control.
Do Not Use Money You Can See as a Reason to Lose More Money You Actually Have
This is a simple rule, but an important one.
If an app shows:
1,000,000 baht in profit,
but says you need to pay 70,000 baht before withdrawing,
do not let the 1,000,000-baht number become the reason you transfer another 70,000 baht.
At that moment, the 70,000 baht still sitting in your real bank account has clear value.
The 1,000,000 baht may only be a number displayed inside a system controlled by someone else.
Do not exchange real money for the hope of turning a number on a screen into real money.
A Group Chat Where Everyone Is Profitable Can Be More Convincing Than the App Itself
Some people do not trust the app because of the app.
They trust it because of the group.
You may see messages like:
“Another profitable day!”
“Thank you, teacher. I withdrew 80,000 today.”
“Anyone who hasn’t increased their investment yet is really missing out.”
“Tonight’s trade should move strongly.”
There may be screenshots of transfers.
Portfolio screenshots.
Luxury cars.
Expensive meals.
Or constant conversations about profits.
When many people appear to be saying the same thing, it becomes easy to think:
“They cannot all be fake.”
But what you do not know is:
Who are those members?
Are they real investors?
Are some accounts controlled by the same team?
Are the transfer slips genuine?
Are the conversations natural?
Or were they created to produce an atmosphere of success?
The number of people in a chat group is not proof that the investment is genuine.
An “Expert” Who Seems to Predict the Market Correctly May Still Prove Very Little
Another thing that builds trust is someone who appears to understand the market extremely well.
They may say:
“Buy here.”
“Sell now.”
“Gold will rise today.”
“Crypto will move tonight.”
Then the app shows that you made a profit.
You start thinking:
“This person really knows what they are doing.”
But if the platform displaying the prices and profits is controlled by the same people guiding you,
you may not be seeing an independent result.
The system may be able to display results that match the advice you were given.
So do not judge an “expert” only by the profits that appear inside the platform they introduced you to.
How “Just Try a Small Amount” Can Turn Into Your Life Savings
Many victims do not start with greed.
They start with:
“I’ll try 5,000 baht.”
Then the app shows profit.
So they think:
“If I put in 50,000, the return will be much bigger.”
Then the advisor says:
“If you increase to 100,000, you will get a better return.”
Then comes a promotion.
“Deposit today and receive a 20% bonus.”
Then:
“You are only a little short of VIP status.”
The amount gradually grows.
5,000
20,000
50,000
100,000
300,000
Some people begin using savings.
Some sell gold.
Some use credit.
Some borrow money.
Because mentally, they do not feel the money is gone.
They think:
“It is still in my portfolio.”
That is the dangerous gap.
The real money may already have left your control.
But your confidence comes from numbers inside the app.
A Bonus That Looks Like Free Money May Make Withdrawal Harder
Some platforms may say:
“Deposit 100,000 and receive a 30,000 bonus.”
It looks like free money.
But the conditions may say you must:
Trade a certain volume
Maintain a minimum balance
Deposit more
Or wait before withdrawing
In a fraudulent system, the bonus may simply be another number used to make the account balance look larger.
Do not judge whether the offer is good based on the bonus.
Look at whether your original money can actually be withdrawn freely.
“You’re Almost VIP” Can Turn Investing Into a Game
A platform may have levels such as:
Silver
Gold
Platinum
VIP
Diamond
Then it says:
“Only 30,000 more to reach Gold.”
Or:
“VIP members get faster withdrawals.”
The investment process starts to feel like a game.
You feel reluctant to stop because you are “almost there.”
It creates the feeling:
“I’ve come this far. It would be a waste to quit now.”
But a membership level displayed on a screen matters far less than your ability to withdraw your money.
“This Opportunity Is Only Available Tonight” Takes Away Your Time to Verify
Fake investment schemes often depend on urgency.
“Big news tonight.”
“You need to enter before the market opens.”
“This round is only for members.”
“Registration closes in 20 minutes.”
“If you don’t increase your investment now, you will miss the opportunity.”
Urgency takes away the time you would otherwise use to:
Search the company name
Check licensing
Ask someone else
Test a withdrawal
Or rethink the whole situation
Real investments can certainly involve timing and market movement.
But being pressured to make a financial decision without enough time to verify should be a reason to slow down,
not speed up.
If They Keep Trying to Stop You from Withdrawing, Think About Withdrawal Before Adding More
If you say:
“I want to withdraw some profit first.”
And the response is:
“Don’t withdraw yet. You’ll lose the opportunity.”
“Returns are strong right now. Reinvest it.”
“You’ll lose your bonus if you withdraw.”
“Wait two more days and the profit will be much higher.”
Ask yourself:
Why are they so concerned about you taking out your own money?
Testing withdrawal is one of the clearest ways to see the difference between:
“A number in a system”
and:
“Money you actually control.”
If simply asking to withdraw creates pressure, become more cautious.
Do Not Only Look at the Chart — Look at Where Your Money Is Going
When you “invest,” where does the real money go?
That question may be more important than the chart.
Be very cautious if you are asked to transfer money to:
A personal bank account
Different accounts every time
Accounts whose names do not match the company
An “agent account”
A “finance department account”
A “deposit account”
Or several unrelated accounts
The caller may explain:
“It’s the payment gateway.”
“It’s an affiliated company.”
“It’s the dealer’s receiving account.”
“Our collection account is changing.”
These explanations may sound business-like.
But before sending investment money, you should understand clearly who is receiving it and under what legal relationship.
Being in an App Store Does Not Automatically Make the Investment Legitimate
As with other types of apps, finding an app in an official store can reduce some risks compared with downloading from an unknown link.
But it should not be the only reason you trust the investment itself.
You still need to ask:
Who operates the service?
What company is behind it?
Is the business information verifiable?
Who receives the funds?
What exactly is being offered?
How are deposits handled?
And can the provider be verified independently?
The app may look polished.
But you are investing real money.
The company receiving that money deserves more scrutiny than the app icon.
If They Ask You to Download an APK or Private App Link, Be Even More Careful
Some scams require installing an app outside the official store.
They may say:
“This is for members only.”
“This version gives better returns.”
“Download it from the teacher’s link.”
“This is our private system.”
“The store version is not supported.”
That creates two layers of risk.
First, the investment itself may not be genuine.
Second, you do not know what the app is doing on your phone.
If an unverifiable investment also requires you to weaken your phone’s normal security just to participate,
stop and reconsider seriously.
Real Market Prices Do Not Prove the Platform Is Real
This is another point that convinces many people.
The app may display:
Real gold prices
Real cryptocurrency prices
Real market charts
Real financial news
When some of the information matches what you can find elsewhere, you begin to think the whole platform must be real.
But showing real market data does not prove your deposited money was actually invested.
An app or website can display genuine market prices
while separately generating a fake account balance for you.
So:
“The price matches Google”
does not mean:
“My money is really in the market.”
Warning Signs of a Fake Investment App
If several of these appear together, stop adding money and verify first:
A stranger approaches you through chat and recommends an investment.
You meet someone through a dating app or social media and they lead you into investing.
Returns are guaranteed.
They claim losses are rare or there is almost no risk.
The app shows unusually high profits continuously.
You are asked to transfer money to personal bank accounts.
Receiving accounts change frequently.
You are asked to download an app from a link or APK file.
A “teacher” or “expert” gives nearly perfect trading instructions.
Everyone in the group seems to be profitable.
You are constantly pressured to invest more.
You receive bonuses for adding money.
VIP levels are used to push you toward larger deposits.
They discourage withdrawals.
Small withdrawals work, but large withdrawals do not.
You are asked to pay a withdrawal fee.
You are asked to pay tax before withdrawing.
You are asked to pay an account unlocking fee.
You are told to add more money to fix a failed transaction.
Or every payment leads to another new fee.
If this pattern begins to appear, do not wait until everything is gone before stopping.
Before Investing Through an App, Ask Yourself These 8 Questions
- Who is the company actually receiving my money?
- Have I verified that company through a source independent of the person who invited me?
- Whose name is on the bank account I am transferring money to?
- If I want to withdraw my original capital now, can I?
- Is there a clear explanation for where the returns come from?
- What will genuinely happen if I do not add more money today?
- Why do I need to send new money in order to withdraw old money?
- If I close every chat with the person who introduced me, can I still contact the company through an official channel?
Number eight is especially important.
If everything disappears when the LINE contact disappears,
you may not have the kind of relationship you thought you had with a real financial institution.
Testing Withdrawal Matters More Than Watching the Profit Percentage
People often ask:
“How much profit am I making?”
A more useful question is:
“Can I withdraw?”
And not only 500 or 1,000 baht.
Ask whether:
You can withdraw your original capital.
You can withdraw a meaningful amount.
There are restrictions.
There are fees.
And whether those conditions were clearly explained before you deposited money, or only appeared when you tried to withdraw.
A 40% profit that cannot be withdrawn may be worth less than 100% of your original money still sitting safely in your own bank account.
If a Withdrawal Fails, Do Not Immediately Solve It by Depositing More
If the system says:
Withdrawal failed.
Account locked.
Verification required.
Do not make your first response:
“Deposit more money.”
Stop first.
Save screenshots.
Save messages.
Save the platform name.
Save the bank accounts you transferred to.
Then verify independently.
If every problem has the same solution:
“Send more money,”
that is not something you should continue without serious verification.
The More You Have Already Paid, the Harder It Becomes to Stop
Imagine you have already put in 300,000 baht.
When you begin to suspect something is wrong, it can be emotionally difficult to accept that the money may be at risk.
Because accepting the possibility means admitting that 300,000 baht may not come back.
That makes statements like:
“Just pay another 30,000 and you can withdraw everything”
very powerful.
This does not happen because people are foolish.
Human beings naturally resist accepting losses.
A useful rule here is:
Money already paid should not become the reason to pay more unless there is new, independently verifiable evidence.
What Should You Do If You Suspect a Fake Investment App?
First, stop sending more money.
Do not immediately pay the next “withdrawal fee.”
Save as much evidence as possible.
For example:
App name
Website
Links
Name of the person who introduced you
LINE account
Phone number
Chat groups
Messages
Portfolio screenshots
Deposit and withdrawal history
Bank account numbers
Account holder names
Transfer slips
Dates and times
Amounts
And messages demanding more payments
If you downloaded an APK or private app file, keep information about where it came from as well.
Then contact your bank through official channels if transfers were involved.
Report the incident through the appropriate channels.
Do not delete the chats because you feel embarrassed.
If the Investment App Requests Remote Access or Strange Permissions, Treat That as Another Serious Risk
Investment fraud and phone-data theft can happen together.
If the investment platform asks you to:
Enable Accessibility
Share your screen
Allow an officer to remotely control your device
Open mobile banking for them to see
Or provide an OTP
stop immediately.
An investment should not require a stranger to control your phone.
What began as investment loss could expand into risk to your other financial accounts.
If You Realize You May Have Been Scammed, Do Not Keep It to Yourself
Some people are afraid to tell their family.
Maybe the money came from savings.
Maybe someone warned them earlier.
Maybe they borrowed money to invest.
Or maybe they feel:
“I should have known better.”
But handling the situation alone can leave scammers more room to keep applying pressure.
They may say:
“Do not tell anyone. It could affect the withdrawal.”
“Other people do not understand the system.”
“Only members understand how this works.”
If you become suspicious, bring in someone you trust.
A person who has not been emotionally involved in the conversations from the beginning may see warning signs more clearly.
Families Should Help First, Not Say “I Told You So”
If someone tells you:
“I can’t withdraw the money,”
the first thing to help with is figuring out:
How much was transferred?
Which accounts received it?
Are they still being asked to send more?
What information has already been shared?
What apps were installed?
Was Remote Access involved?
What evidence is available?
Saying:
“I told you not to invest”
does not bring the money back.
Stopping the next transfer might still save money that has not yet been lost.
Do Not Blame Yourself for Trusting a Profit You Could See
If you saw profits rising inside the app,
successfully withdrew a small amount,
saw other people posting transfer slips,
and spoke to the same people for weeks,
it is not surprising that the system began to feel real.
Sophisticated scams do not try to look suspicious.
They try to look trustworthy.
The important moment comes when things stop making sense.
For example:
You cannot withdraw.
You must send more money.
The rules suddenly change.
New fees appear.
Or the pressure increases.
At that point, return to the most important question:
Where is my real money right now?
A Sentence to Remember: Profit You Cannot Withdraw Is Not Profit You Should Count
If you remember only one sentence from this article, remember this:
Profit you cannot withdraw is not profit you should count.
A chart can stay green.
Your balance can rise.
Bonuses can increase.
Your VIP level can improve.
But all of those things still exist inside a system someone else controls.
What matters is:
Can you withdraw your original money?
Do you control the funds?
And do you have to send new real money every time you try to take your old money out?
If the answer keeps becoming:
“Pay more first,”
stop.
Conclusion: Fake Investment Apps Often Do Not Scam You with “Losses” — They Scam You with “Profits”
Many people assume a scammer will make their money disappear.
A fake investment app may do the opposite.
It may make the money on the screen grow.
Because when you see:
10,000 become 15,000
50,000 become 80,000
200,000 become 350,000
you naturally want to add more.
And the higher the displayed balance becomes, the more willing you may be to pay new fees in the hope of withdrawing it.
That is the part to watch most carefully.
Before adding capital,
test withdrawal.
Before trusting the profit,
verify who actually received your money.
Before sending money to a new account,
ask why the receiving account changed.
Before paying a withdrawal fee,
ask why it cannot be deducted from the existing balance.
And before trusting the chart,
ask where your real money is.
Because in investing,
the most beautiful number is not the profit displayed on a screen.
It is the money you can still control and genuinely return to your own account.
Leave a Reply
You must be logged in to post a comment.